Distressed Property Sales & Foreclosures in Mobile, AL
In Mobile, AL, homeowners who explore distressed property sales and foreclosure options before a foreclosure sale date often have more choices, including lender relief, a short sale, or a traditional sale. Financial hardship, missed payments, inherited repair needs, or a home in poor condition can make selling feel overwhelming, but an early plan can reduce uncertainty.
The most practical first step is to understand the deadline, gather loan and property documents, and get qualified guidance about the available paths. Each situation has different financial, legal, and property-condition factors, so acting before the process becomes more urgent can help clarify what remains possible.
What Makes a Property "Distressed"?
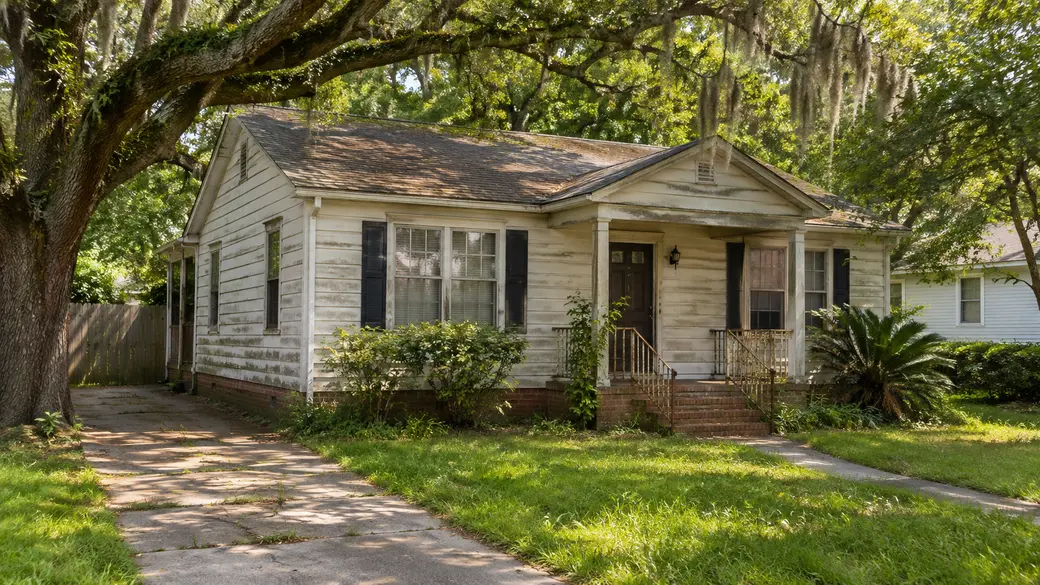
A distressed property is a home affected by financial pressure, major condition concerns, or both. Financial distress may involve missed mortgage payments, lender notices, unpaid property taxes, or a pending foreclosure process. Physical distress can include extensive deferred maintenance, storm damage, vacancy, code issues, or repairs the owner cannot reasonably complete before selling.
A home does not have to be headed to foreclosure to be distressed. Some Mobile homeowners have equity but need a sale strategy that accounts for repairs, cleanup, timing, or an inherited property's condition. Others need to make decisions quickly because missed payments and lender communications are creating immediate pressure.
The appropriate path depends on the mortgage balance, estimated sale value, condition, available time, and the owner's broader financial goals. Reviewing those factors early helps distinguish urgent deadlines from options that may still be available.
How Foreclosure Generally Works
Foreclosure generally begins when a borrower falls behind on mortgage payments and the lender starts the process permitted by state law. Lenders may issue notices, discuss loss-mitigation options, and eventually pursue a foreclosure sale if the default is not resolved.
Alabama commonly permits nonjudicial foreclosure when a mortgage includes a power-of-sale provision, meaning a court case is not always required before a foreclosure sale. The exact process can vary based on the loan documents, title concerns, legal disputes, and other circumstances. A homeowner who receives a serious delinquency notice should seek prompt guidance from a qualified Alabama real estate attorney or HUD-approved housing counselor.
Mortgage foreclosure and unpaid-property-tax matters are separate processes. Since tax year 2019, the Mobile County Revenue Commission has collected delinquent real-property taxes through tax lien auctions rather than selling the property itself, and its 2026 online auction began on May 11, 2026. Delinquent taxpayers are mailed notice at least 30 days before the auction. A tax-lien purchaser receives a lien certificate, not title or a right to possess the property, and redemption rights may apply under Alabama law. The Mobile County Revenue Commission's tax lien sale information provides further local process details.
Options Before Foreclosure
Options before foreclosure can include a loan modification, forbearance, repayment plan, short sale, deed in lieu of foreclosure, or a traditional sale. The right choice depends on whether the homeowner wants to keep the property, can resume payments, has equity, and has enough time to complete the selected path.
| Option | May Fit When | Main Limitation | Confirm First |
|---|---|---|---|
| Loan modification | The owner wants to keep the home and may be able to manage adjusted payments | Lender approval is required | Proposed payment, loan term, and total obligation |
| Forbearance | A temporary hardship affects the owner's ability to make payments | Missed amounts may still need repayment later | Repayment terms after the forbearance period |
| Repayment plan | Income has resumed and the owner can address missed amounts over time | Future payments may be higher | Monthly payment amount and schedule |
| Short sale | The likely sale price is below the mortgage payoff | The lender must approve the transaction | Whether the lender will release the remaining debt |
| Traditional sale | Expected proceeds can cover payoff and closing costs | Timing and condition can affect marketability | Estimated net proceeds and closing timeline |
| Deed in lieu | Selling is not practical and the lender is willing to accept the property | It is not automatically available | Lender requirements and potential financial consequences |
A loan modification may change certain loan terms, while forbearance may temporarily reduce or pause payments under an approved agreement. A repayment plan can spread missed amounts across future payments. Because these options depend on lender approval, homeowners should request written terms and understand the total obligation before agreeing to a plan.
When keeping the property is no longer realistic, a sale may provide a more controlled outcome. A conventional sale can work when expected proceeds cover the payoff and closing costs. When the likely sale price is below the total amount owed, a short sale may be an option to discuss with the lender.
A property's estimated value and likely sale costs are important starting points for deciding whether a traditional sale is realistic. A current value estimate for your home can help you compare expected proceeds with mortgage payoff information, likely repair costs, and the time available before choosing a path.
Selling During Pre-Foreclosure
Selling during pre-foreclosure can preserve more choices because the owner may still have time to market the home, consider offers, and coordinate with the lender. Waiting until a scheduled sale date can reduce flexibility and make every decision more urgent.
Homeowners should gather mortgage statements, delinquency notices, payoff information, tax records, and correspondence from the lender or servicer. These documents help clarify the amount that must be addressed at closing and allow an attorney, housing counselor, or real estate professional to assess whether a conventional sale, short sale, or another approach is realistic.
A property does not need to be fully renovated to be marketable. In Mobile, a well-priced home with clear disclosures and a practical preparation plan may still attract buyers when repairs are needed. The objective is not necessarily to make the home perfect. It is to select a sale approach that fits the condition, deadline, and seller's resources. The typical stages of a Mobile home sale still apply, just on a tighter, more deliberate schedule.
Short Sales Explained
A short sale is a negotiated transaction in which the lender agrees to accept less than the full mortgage balance from the sale proceeds. It requires lender approval and differs from simply listing a home below the loan payoff amount.
The seller commonly provides financial documents, a hardship explanation, a buyer offer, and property information. The lender reviews the proposed terms and decides whether to approve the short payoff. Because the lender is part of the transaction, organized documentation, realistic pricing, and careful communication are important.
A short sale may allow an owner to avoid a foreclosure sale, but it can still involve credit, tax, and legal consequences. Sellers should seek advice from an attorney and tax professional before relying on a short-sale outcome. Written lender approval should be reviewed carefully to determine whether any remaining obligation could continue after closing.
Selling As-Is or Quickly
Selling as-is can be appropriate when repairs, cleanup, time constraints, or financial pressure make a full renovation unrealistic. An as-is sale means the property is offered in its current condition while the seller continues to follow applicable disclosure obligations.
The tradeoff often involves price, buyer expectations, and the size of the potential buyer pool. Some buyers may be prepared to handle repairs, while others may be limited by financing or condition requirements. Sellers can improve the likelihood of a workable transaction by clearly communicating known issues, removing belongings where possible, and setting a price that reflects both the home's strengths and needed work.
Speed matters in a distressed sale, but it should not automatically outweigh every other consideration. When an owner has equity or some flexibility, comparing likely proceeds, timing, and certainty across more than one path can support a better-informed decision.
Pricing a Distressed Property
Pricing a distressed property requires a realistic assessment of condition, local buyer demand, repair needs, and the seller's timeline. An asking price that is too high can delay the sale, while an unnecessarily low price may reduce the owner's remaining equity.
A useful pricing review considers recent comparable sales, active competition, neighborhood demand, visible condition concerns, and the work a buyer is likely to take on after closing. Vacancy, water intrusion, roofing concerns, or extensive deferred maintenance can influence how buyers evaluate the home.
Urgency should be handled strategically. Sellers facing a deadline may benefit from a price and marketing plan designed to generate credible interest promptly rather than repeated reductions without a clear market rationale.
Buying Distressed Properties
Buying distressed properties can create opportunities for buyers, but it also introduces risks that sellers should understand when evaluating offers. Buyers considering homes that need repairs may account for condition, financing limits, title questions, occupancy issues, and potential holding costs before deciding whether to proceed.
For a seller, this means the highest initial offer is not always the only relevant factor. The reliability of financing, the buyer's understanding of the property's condition, the requested closing schedule, and the likelihood of completing the transaction can all matter. A clear property description and sensible pricing strategy can help attract buyers whose expectations align with the home's condition.
Where to Get Help
HUD-approved housing counselors, which may provide free or low-cost assistance, qualified Alabama real estate attorneys, and tax professionals can help homeowners understand options before foreclosure or a distressed sale. These professionals serve different roles, and more than one source of guidance may be appropriate when a situation involves a mortgage, taxes, title, or possible legal consequences.
HUD-approved counselors can help homeowners review loss-mitigation options, organize financial information, and communicate with mortgage servicers. The U.S. Department of Housing and Urban Development offers foreclosure-avoidance counseling resources for homeowners seeking approved assistance.
An attorney can explain Alabama-specific rights, deadlines, documents, and potential consequences. A tax professional can address questions involving canceled debt, capital gains, inheritance, or other tax issues. Real estate guidance can then focus on property value, marketability, buyer interest, and the practical steps required to complete a sale.
Distressed property sales and foreclosures in Mobile, AL can feel urgent, but acting early usually keeps more options on the table. Whether the challenge involves missed payments, tax delinquency, a short sale, or substantial repair needs, a clear plan can reduce uncertainty and support more informed decisions.
Gather key documents, understand the relevant deadlines, and seek appropriate professional guidance before signing an agreement or making a major decision. The goal is not to force one solution. It is to identify the path that best fits the property, finances, and next steps.
Talk Through Your Options Confidentially
Sheri Jones of Foundation First Real Estate represents Mobile homeowners in short sales, as-is sales, and other distressed property transactions, working alongside the attorneys, housing counselors, and lender loss-mitigation teams involved. Conversations are confidential and come with no obligation. Call (251) 377-5974, email sheri@tomandsherijones.com, or use the contact page to talk through your situation.
What you get when you reach out:
- A confidential review of your situation and selling options
- A current home value estimate to compare with what you owe
- Referrals to housing counselors, attorneys, and lenders' loss-mitigation contacts
FAQ
Can I sell my house if I'm behind on payments?
Selling may still be possible while payments are overdue, provided the foreclosure sale has not been completed and there is sufficient time to close. Sale proceeds must address the mortgage payoff, closing costs, and other required amounts. If the expected sale price is below the full amount owed, lender approval may be needed.
What is the difference between a short sale and foreclosure?
With a short sale, the lender approves a sale for less than the mortgage payoff while the homeowner remains involved in the transaction. Foreclosure is the lender's process for taking and selling the property after default. Short-sale approval is not guaranteed, but it can give the seller more participation than a completed foreclosure.
How long does foreclosure take?
The timeline depends on the loan documents, lender actions, notice requirements, legal issues, and property-specific circumstances. Alabama commonly allows nonjudicial foreclosure, which can move differently from a court-based process, so prompt local legal or housing-counseling guidance is important after notices arrive.
What happens if I fall behind on property taxes in Mobile County?
Mobile County generally sells a tax lien on the delinquent amount at an annual online auction rather than selling the home itself. The lien purchaser does not receive title or possession, and redemption rights may apply. Contact the Mobile County Revenue Commission or an attorney as soon as possible to understand your payoff and redemption options.
Where can I get free foreclosure help?
HUD-approved housing counseling agencies may offer free or low-cost foreclosure-prevention assistance and can help homeowners understand lender communications and loss-mitigation choices. Homeowners can use HUD resources to locate an approved counseling agency and should be cautious of anyone requesting upfront fees for foreclosure relief.
Recent Posts